Why Downsizing Could Make Sense for You in 2027
24 September 2026
Downsizing has always carried a whiff of compromise. The word itself suggests loss, as if you are giving something up rather than gaining something back. That framing made sense in an era when a smaller home usually meant a lesser one. It makes far less sense in 2027, when the calculus behind housing choices has shifted in ways that reward flexibility, lower carrying costs, and the ability to redirect equity toward things that actually improve your life.
This is not a pitch to sell your house. For many people, staying put is the smarter move. But for a growing number of homeowners, the numbers and the lifestyle math now point in a different direction. What follows is an honest look at when downsizing works, when it backfires, and how to tell the difference before you list your property.
The 2027 Context That Changes the Math
Housing decisions do not happen in a vacuum. They happen inside a specific market, a specific tax environment, and a specific stage of your life. Three forces are shaping downsizing decisions more than any others right now.First, carrying costs have become the dominant expense in homeownership for many households. Property taxes, insurance premiums, utilities, maintenance, and HOA dues have climbed faster than many owners anticipated when they bought. A larger home amplifies every one of those line items. The mortgage balance is only part of the story. Two houses with identical mortgages can differ by hundreds of dollars a month in operating costs, and that gap compounds over years.
Second, the equity many long-term owners hold is substantial. If you bought a decade or more ago and have paid down the loan while values rose, you may be sitting on a large, illiquid asset that produces no income and requires constant spending to maintain. Downsizing converts part of that trapped equity into cash or into a smaller, more manageable obligation.
Third, remote and hybrid work have loosened the tie between where you live and where you earn. Someone who no longer commutes five days a week can consider locations that were previously off the table, which widens the field of smaller, cheaper, or better-situated homes.
None of these forces automatically favor downsizing. But together they mean the decision deserves a fresh look rather than a default assumption that bigger is better and staying is safest.
What Downsizing Actually Means
People use the term loosely, and that looseness causes bad decisions. Downsizing can describe at least four different moves:- Reducing square footage while staying in the same area
- Reducing monthly costs even if square footage stays similar
- Trading a single-family house for a condo, townhouse, or rental
- Relocating to a lower-cost region entirely
These are not interchangeable. A person who sells a 3,000 square foot house and buys a 1,800 square foot house nearby has downsized space but may not have reduced costs much if the new home is in a pricier neighborhood. Someone who moves from a large house to a smaller home in a cheaper state has downsized both space and cost, but taken on the disruption of leaving a community.
Before you decide whether downsizing makes sense, decide which version you are actually considering. The financial and emotional consequences differ enormously.
The Financial Case, Honestly Examined
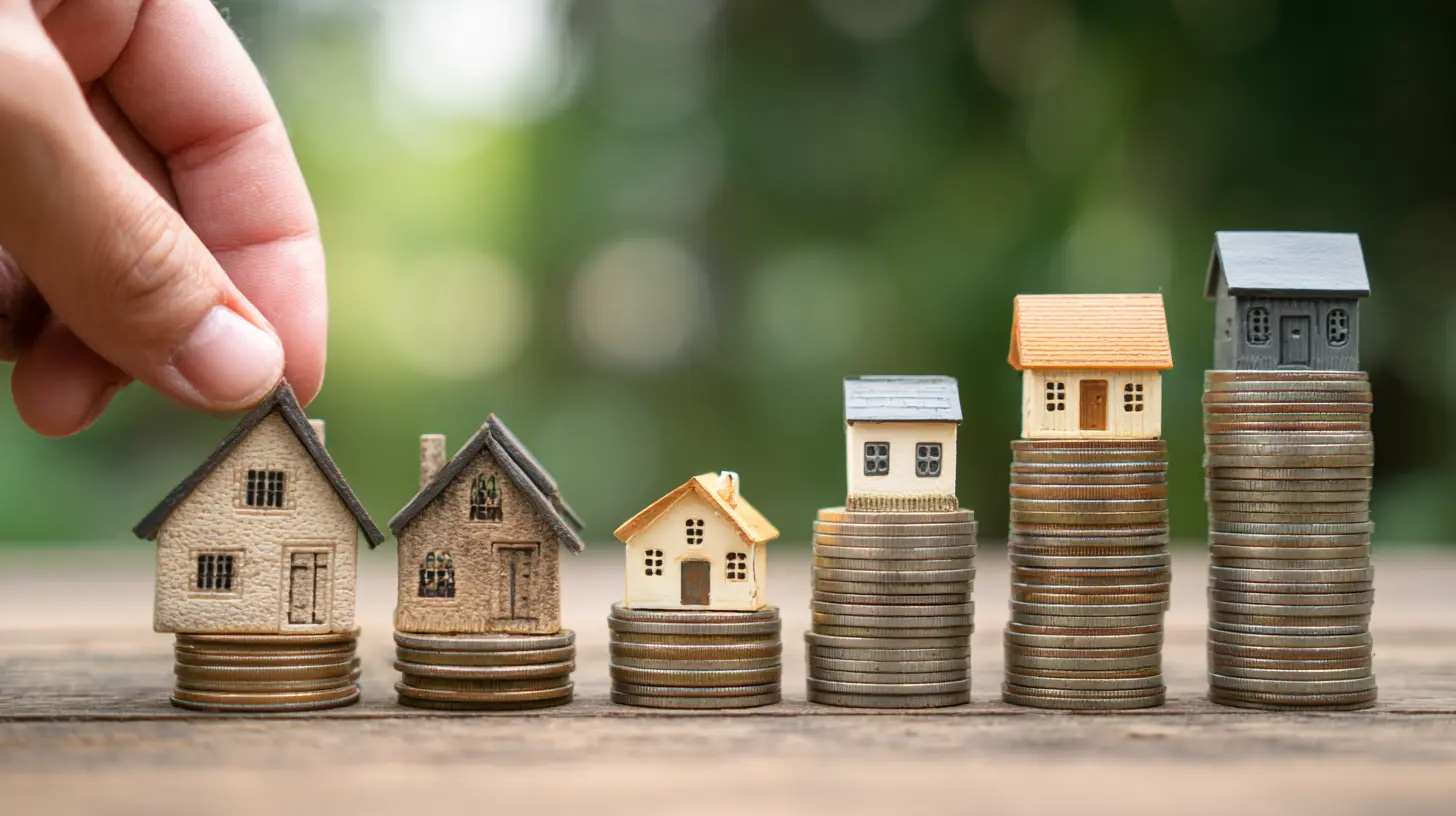
The strongest argument for downsizing is usually financial, so it deserves the most scrutiny. The headline benefit is unlocking equity. If you sell a home worth $600,000 with a $150,000 mortgage and buy a $350,000 home outright, you have freed roughly $100,000 in cash after typical selling costs and the new purchase. That money can fund retirement, pay off debt, or simply sit as a reserve.But the headline number hides real costs. Selling typically involves agent commissions, title and escrow fees, transfer taxes, and concessions to buyers. Buying involves loan origination, appraisal, inspection, and moving expenses. It is not unusual for the round trip to consume 8 to 12 percent of the sale price once everything is counted. On a $600,000 sale, that could be $50,000 to $70,000 gone before you see a dollar of equity.
Then there is the ongoing cost comparison. A smaller home usually costs less to heat, cool, insure, and maintain. A condo often shifts exterior maintenance to the association, which can be a genuine relief, but the monthly HOA fee may offset much of the savings. Some associations levy special assessments for roofs, elevators, or structural repairs that can run into five figures. Read the reserve study and the meeting minutes before you buy into any association. That is where the real financial picture lives.
When the Numbers Favor Downsizing
Downsizing tends to pencil out well when several of these are true:- You have owned the home long enough to have substantial equity.
- Your current home has high operating costs relative to its size.
- You are paying for space you no longer use.
- You are willing to move to a lower-cost area or a less expensive property type.
- You value liquidity and lower fixed costs more than square footage.
When the Numbers Argue Against It
Downsizing often disappoints when:- You bought recently and have little equity after selling costs.
- The smaller home costs nearly as much per square foot because of location.
- High HOA fees erase the maintenance savings.
- You would need a new mortgage at today's rates to make the move.
- Transaction costs would consume most of the equity you hoped to free.
Run the full arithmetic, not just the sticker prices. A spreadsheet that ignores commissions, moving costs, and HOA dues will flatter downsizing every time.
The Lifestyle Case, Which Often Matters More
Money is measurable, which is why it dominates the conversation. But most people who are glad they downsized cite non-financial reasons first. The house that suited a family of five feels like a burden when two people live in it. Rooms sit unused. Cleaning takes a full day. Repairs arrive faster than you can address them. A smaller home can feel like relief rather than reduction.There is also the matter of what you do with the freed-up resources. Lower housing costs can fund travel, help adult children, support hobbies, or simply reduce financial stress. That last one is hard to overstate. A mortgage or tax bill that keeps you awake at night is a real cost, even if it never appears on a ledger.
Counterweights exist here too. A large home often holds a workshop, a garden, a guest room, or space for grandchildren. Giving those up has a price that does not show up in any calculator. Some people downsize and then spend the savings renting storage units or paying for hotel rooms when family visits. That is a sign the move was too aggressive.
The Emotional and Social Dimension
Homes are not just assets. They are the physical container of memory, routine, and relationship. Leaving a house where you raised children or buried a spouse is not a purely rational transaction, and pretending otherwise sets people up for regret.Neighbors matter more than most buyers admit. A downsized home in the same neighborhood preserves the social network that makes daily life pleasant. A cheaper home two states away may improve the balance sheet while quietly isolating you. Before committing to a move, ask what your ordinary Tuesday would look like in the new place. If you cannot picture it clearly, you may be optimizing for the wrong variable.
Timing: Why 2027 Specifically
Every year is a downsizing year for someone. But 2027 has features that make the decision worth revisiting.Interest rates shape the trade-off between carrying a mortgage and paying cash. When rates are high, buyers who can pay cash for a smaller home gain a real advantage, because they avoid financing costs entirely. When rates are low, the advantage of freeing equity shrinks, since borrowing is cheap. The right move depends on where rates sit when you act, not where they sat when you last checked.
Tax rules also matter. Capital gains exclusions on a primary residence allow many sellers to exclude a significant portion of profit, but the rules have thresholds and holding-period requirements. If your gain would exceed the exclusion, the tax bill can be substantial. This is one area where a conversation with a tax professional is worth far more than any general article, because the answer depends on your basis, your filing status, and your history with the property.
Local market conditions matter too. In a slow market, your home may take months to sell and require price cuts. In a fast market, you may sell quickly but struggle to find a replacement. Downsizers face a particular version of this problem because they are both selling and buying, often in the same market at the same time. In tight inventory, consider whether you can rent temporarily or negotiate a rent-back so you are not forced into a rushed purchase.
Common Mistakes and Misconceptions
A surprising number of downsizing decisions go wrong for predictable reasons. Avoiding these traps is more valuable than any single piece of advice.Mistake: Assuming smaller always means cheaper. A smaller home in a prime location can cost more per square foot than a larger home in a modest one. Compare total monthly cost, not size.
Mistake: Ignoring the true cost of the move. Commissions, taxes, movers, and new furnishings add up. Budget them before you commit.
Mistake: Downsizing too far, too fast. Going from 3,000 square feet to 800 square feet in one step is jarring for many people. A middle step often works better.
Mistake: Overlooking HOA risk. Special assessments can wipe out years of savings. Investigate the association's finances before buying.
Misconception: Downsizing means downgrading. Many smaller homes are better built, better located, and better suited to their owners than the large house they replaced.
Misconception: You must decide once and forever. Downsizing can be a temporary move. Some people sell the big house, rent for a year, and then choose a permanent home with better information.
A Practical Framework for Deciding
If you are on the fence, work through these questions in order. They mirror how a careful advisor would think through the problem.1. What is my current total monthly cost of housing, including taxes, insurance, utilities, maintenance, and HOA dues?
2. What would that number be in the smaller home I am considering, all in?
3. What is my realistic equity after selling costs?
4. What would I do with the freed equity, and does that use beat the value of staying?
5. Can I picture my daily life in the new place, including how I would spend my time and who I would see?
6. What would I miss, and can I replace it another way?
7. What is my fallback if the sale or purchase does not go as planned?
If the answers point clearly in one direction, act. If they are mixed, consider a trial run. Renting in the target area for six months is a cheap way to test a decision that is expensive to reverse.
Alternatives Worth Considering Before You Sell
Downsizing is not the only way to capture the benefits people associate with it.- Renting out part of your home. A basement apartment or accessory dwelling unit can offset costs without a move. This works best where local rules permit it and where you can tolerate sharing space.
- A reverse mortgage. For older homeowners with substantial equity, this can provide income while you stay put. It carries real costs and complexity, so it deserves careful study rather than a quick yes.
- Refinancing or recasting. If the goal is a lower monthly payment rather than less space, adjusting the loan may achieve it without moving.
- A life estate or sale-leaseback arrangement. These structures let you unlock equity while remaining in the home. They are niche and require professional guidance.
- Staying put and cutting other costs. Sometimes the housing is fine and the budget pressure is coming from somewhere else.
Each of these has trade-offs. None is universally right. The point is that downsizing is one option among several, and it should compete against them rather than stand alone.
Making the Move Work
If you decide to downsize, execution matters as much as the decision. A few practices separate smooth transitions from painful ones.Start decluttering a year ahead if you can. Sorting decades of possessions is slower than anyone expects, and rushing it leads to bad choices about what to keep. Measure the new home's storage before you commit, including closets, cabinets, and garage space. A floor plan that looks adequate on paper can feel cramped once furniture arrives.
Time your sale and purchase carefully. In a balanced market, selling first and renting briefly gives you leverage as a buyer and removes the pressure of a contingent offer. In a hot market, the reverse may be safer. Talk to an agent who has handled downsizers specifically, not just any agent. The dynamics are different from first-time buyer transactions.
Finally, treat the move as a transition rather than an ending. Give yourself a few months to adjust before judging whether it was the right call. Most people who regret downsizing do so in the first ninety days, when the newness has worn off and the old routines are gone. Most who are glad they did it feel that way after a year, once new routines have taken root.
The Bottom Line
Downsizing in 2027 can be one of the most financially and personally rewarding moves a homeowner makes. It can also be a costly mistake driven by assumptions rather than arithmetic. The difference comes down to doing the work: understanding your true costs, comparing total outcomes rather than sticker prices, testing the lifestyle before you commit, and being honest about what you would gain and what you would give up.If the numbers work and the life you picture in a smaller home appeals to you, the case for moving is strong. If either piece is missing, waiting costs you nothing but time. The decision belongs to you, and it deserves better than a rule of thumb.
all images in this post were generated using AI tools
Category:
Selling A HomeAuthor:
Lydia Hodge